
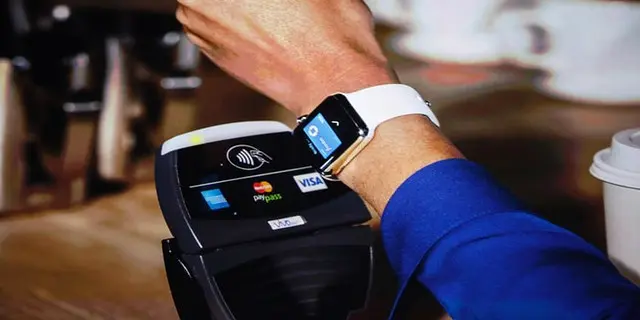
South Africa can build faster payment systems, introduce smarter banking technology and bring artificial intelligence into financial services. But these advances will mean little if people cannot afford digital payments, struggle to access them or do not trust them with their money.
While financial institutions prepare for a new generation of payment technology, cash remains firmly rooted in everyday life. The South African Reserve Bank’s 2026 Cost of Cash Research Study found that cash accounted for about 56% of consumer transactions by volume, based on 2024 data.
For many South Africans, payment choices are shaped by transaction fees, access to reliable internet, whether businesses accept digital payments and how easily they can recover their money when something goes wrong. A technologically advanced payment system can fail to meet these needs.
South Africa’s instant payment service, PayShap, illustrates the challenge. Introduced in 2023 to make bank transfers quicker and easier, it has faced barriers to adoption, including differences in bank functionality, pricing and merchant acceptance.
The question is not simply whether a service exists but whether people understand it, can afford it and have reason to change their habits.
At the BPC Client Conference 2026 in Cape Town this week, Maxim Pavlov, the chief technology officer at payment technology company BPC, said banks must modernise without putting services at risk. He described the approach as “evolution rather than revolution”.
Many banks rely on older technology that can be expensive to maintain and difficult to adapt. Replacing entire systems can be disruptive, while modular architecture allows institutions to update parts of their infrastructure without rebuilding everything at once.
BPC’s SmartVista platform uses a modular, API-driven approach designed to support cloud-based and on-premise deployments. The aim is to help banks adapt as payment methods and customer expectations change.
But modernising banking infrastructure is not the same as improving customers’ financial lives. Whether better systems translate into lower costs, wider access and more useful services depends on how the technology is deployed.
Artificial intelligence (AI) could further change financial services. Pavlov discussed BPC’s development of AI capabilities, including tools to monitor systems, identify potential incidents and recommend action. Other possible applications include fraud prevention, personalised customer engagement and financial advice.
Earlier detection of system problems could help prevent service interruptions, while improved fraud detection could strengthen customer protection. But AI can also make mistakes, raise privacy concerns and leave customers uncertain about who is responsible when something goes wrong.
Financial institutions will need to ensure that efficiency does not come at the expense of transparency, accountability and trust.
Technology also places pressure on those deciding how it should be used. At the conference, Avil Ruthipaul, the chief information officer for lending products at Standard Bank, discussed the strain on leaders navigating competing priorities, constant communication and a steady stream of new technologies.
He warned that decision fatigue could lead organisations to continue with projects that no longer made sense, leaving them with technical and organisational debt that ties up resources.
As businesses rush to adopt AI, new tools may improve productivity but expecting stretched teams to do more could create further pressure.
For South Africa, the choices have consequences beyond banks and technology companies. Small businesses need affordable, dependable ways to accept payments.
Consumers need to understand what they are being charged and trust that their money is safe. People who continue to use cash should not automatically be treated as resistant to progress. Their choices may reflect the costs and limitations of the alternatives available to them.
The next phase of digital payments should be judged by more than transaction volumes, new platforms or sophisticated AI tools. It should be measured by whether people can pay safely and affordably, smaller businesses can accept digital payments without prohibitive costs and services remain reliable when technology fails.
South Africa does not lack ambition when it comes to modernising its financial system.
The harder task is ensuring that innovation benefits the people expected to use it. The future of payments will depend not only on how quickly money moves but on who can participate, what it costs and whether people trust the systems on offer.